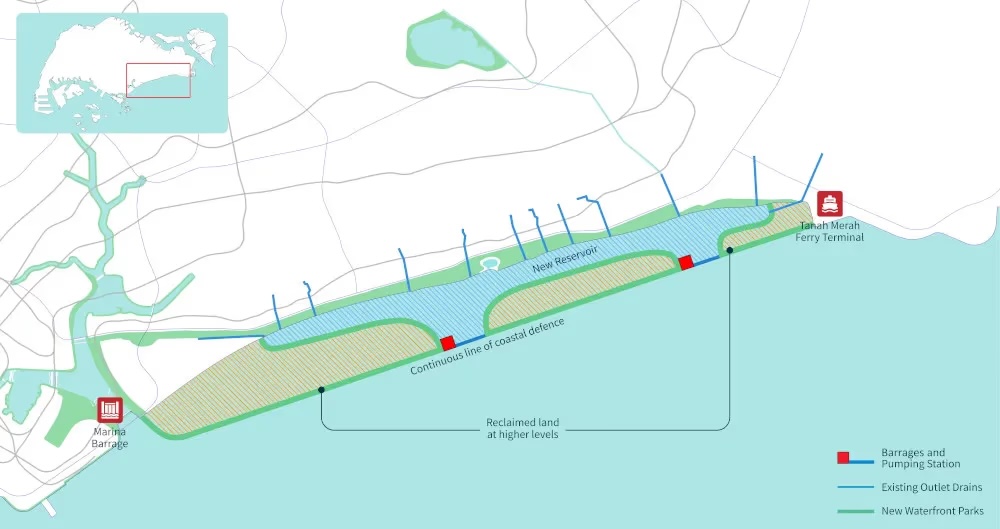
Long Island Singapore is a coastal protection project that will also create land off the East Coast shoreline. It is no longer a study. The environmental impact report was released on 30 June 2026, and preparatory works begin off East Coast Park at the end of 2026.
That makes this the quiet conversation in 4 specific projects, and it is no longer hypothetical.
Mandarin Gardens, Neptune Court, Laguna Park and Lagoon View hold 2,753 households between them. All 4 sit in the Siglap subzone, all 4 are 99-year, and all 4 look out over the water that Long Island would sit on.
If you own in one of them, you have probably been told your view is finished and your en bloc is dead. Neither claim is supported by the transaction record. Here is what is.
Long Island is coastal protection first. Sea level rise is the driver. Creating land is a consequence of defending the coast, not the purpose of it. It was first floated in the 1991 long-term plan and has since grown into a defence project that also delivers a reservoir and land for future needs.
The position changed on 30 June 2026, when URA and HDB released the environmental impact report and set out the phasing.
Preparatory works start at the end of 2026, in 2 phases around Bedok Jetty.
Phase 1 runs west of the jetty, covering roughly 570 hectares and spanning about 7 kilometres. That is the phase beginning at the end of 2026.
Phase 2 runs east of the jetty, covering about 155 hectares, and only starts after Singapore hosts its major international sporting events, including the SEA Games in 2029. Sport Singapore has confirmed the waters east of Bedok Jetty stay open for sea sports until at least 2029. The start date for that phase has not been firmed up.
Together the works cover about 725 hectares of sea space, roughly twice the size of Marina Bay.
Preparatory works means clearing seabed obstructions, building temporary sand bunds, and moving sand for infilling. It is not the finished reclamation.
The agencies also expect some impact on biodiversity, including the critically endangered hawksbill turtle that nests at East Coast Park, and say park activities and nearshore swimming continue with minimal disruption. Sea sports are the real casualty, with kiteboarding most affected.
Here is the part that matters most to an owner, and it is a direct quote of the agencies’ own position: no end date has been given, and HDB describes Long Island as expected to take decades to plan, design and implement.
So the honest summary has changed. This is no longer a study that may never happen. It is a project with a start date, an unpublished finish date, and a horizon measured in decades.
These are not boutique blocks. They are 4 of the largest projects on the East Coast, and they were built when the shoreline was newer than they were.
| Project | Units | Completed | Lease from | Lease left in 2026 |
| Mandarin Gardens | 1,006 | 1986 | 1982 | 55 years |
| Neptune Court | 751 | 1975 | 1975 | 48 years |
| Laguna Park | 516 | 1978 | 1977 | 50 years |
| Lagoon View | 480 | 1977 | 1977 | 50 years |
Mandarin Gardens alone is 1,006 units, which makes it larger than most new launches in the district. Together the 4 are 2,753 homes, or roughly 8% of every condo unit in the whole of District 15.
That scale matters for what follows. A concern shared by 2,753 households moves a market. A concern shared by 40 does not.
Here is the part that gets lost. Every one of these 4 projects was already on a shortening clock before Long Island was ever mentioned.
Neptune Court’s lease started in 1975. That leaves 48 years. Laguna Park and Lagoon View started in 1977, leaving 50 years. Mandarin Gardens is the youngest at 1982, leaving 55 years.
All 4 are now under 60 years of remaining lease. That is the threshold where financing and CPF usage start to tighten for buyers, which narrows the pool of people who can buy your unit. [VERIFY: current CPF usage and loan-to-value rules by remaining lease, from CPF and MAS source pages]
Now look at what the resale market has actually done with that.
| Project | Median psf | Resales recorded | 2021 median | 2026 median |
| Mandarin Gardens | $1,283 | 148 | $1,115 | $1,291 |
| Neptune Court | $1,017 | 132 | $927 | $1,067 |
| Laguna Park | $1,177 | 79 | $1,071 | $1,239 |
| Lagoon View | $1,142 | 41 | $1,105 | $1,187 |
Every one of the 4 is worth more per square foot in 2026 than in 2021. Neptune Court is up $140 psf over the period. Laguna Park is up $168 psf.
That is a market pricing a lease clock, not a reclamation panic.
Worth being precise about the timing. The environmental impact report and the end-2026 start date were announced on 30 June 2026. The 2026 medians above cover January to August, so they straddle the announcement rather than sit cleanly after it. The first clean read on whether buyers care will come from the 2027 numbers.
The one thing worth watching honestly: Mandarin Gardens has gone sideways since 2023, moving $1,311, then $1,327, then $1,284, then $1,291. The other 3 kept climbing. That is 4 years of flat pricing in the largest of the 4 projects, and it is the only soft number in this whole set.
Whether that is Long Island, the lease, or the sheer size of the project taking longer to clear stock, the record cannot tell you. Anyone who says otherwise is guessing.
If you own in one of these 4 and want the specific read on your stack rather than the project average, send me your unit details on WhatsApp and I will pull the comparable sales.
This coast has done this before, and the result is instructive.
Marine Parade is built on reclaimed land. So is most of East Coast Park. Before the reclamation of the 1960s and 1970s, the sea came up to what is now the inland edge of the district. Homes that had water frontage lost it entirely.
Those homes did not become worthless. Marine Parade today holds 7,855 flats and some of the most expensive resale addresses on the coast, and the Marine Parade Condo Guide covers a pocket that only exists because the land was made.
The honest caveat: URA’s public transaction record does not reach back to the 1970s, so there is no price series from that period to hold up. What we have is the outcome, which is a desirable, expensive residential district sitting on made ground, with a large park between it and the water.
That precedent cuts both ways, and it should. Losing an open sea view is a real loss for the specific stacks that have one. Gaining a park, a promenade and coastal protection is a real gain for everyone else. What we know about what a sea view is actually worth applies to the high-floor sea-facing stacks, not to the project as a whole.
The argument you hear is that Long Island kills the en bloc case. Run the numbers and the picture is different, because the numbers were always daunting.
Take the median resale price in each project and multiply by the unit count. That is the rough floor any collective sale has to clear before a single dollar of premium is paid to owners.
Those are floors, not reserve prices. A real collective sale needs a premium on top, and the buyer needs a development charge, a construction budget and a sale price that works at the end of it.
A $1.9 billion floor was a hard sell in 2019 and it is a hard sell now. Long Island did not create that problem, and the preparatory works starting at the end of 2026 do not change the math either. Lease decay is a far more direct threat to a collective sale here, because a shorter lease raises the lease top-up cost the developer has to pay.
The projects most likely to transact are the smaller 2: Laguna Park at 516 units and Lagoon View at 480. That was true before anyone drew a Long Island map.
Different answers for different situations, and none of them is “panic.”
If you are holding to live, keep living there. The resale record shows 4 projects that have gained value since 2021 while the lease shortened. You own a large, well-located home near East Coast Park at a psf far below anything new in the district. Seaside Residences, in the same subzone and completed in 2021, trades at a $2,263 median psf. Neptune Court trades at $1,017. You are holding the affordable end of a very expensive coast.
If you were counting on an en bloc to fund retirement, build a second plan. That was sound advice before Long Island. A $900 million to $1.9 billion collective sale is a low-probability event on any timeline you can plan around.
If you are selling within 5 years, the lease is your issue, not the reclamation. Every year shortens the buyer pool. Price to the market you have rather than the one you had in 2021, and move while the transaction counts are healthy. Mandarin Gardens recorded 31 resales in 2026 and Neptune Court 13, so there is a functioning market to sell into.
If you are buying in, buy with your eyes open. You are buying a shortening lease at a discount, in a project where reclamation works begin at the end of 2026 and run for decades. Both of those are already in the price. What you get in return is space and a location that new stock cannot match at the money.
It has moved well past a study. The environmental impact report was released on 30 June 2026 and preparatory works begin at the end of 2026, starting with a 570 hectare phase west of Bedok Jetty. No completion date has been published.
The first phase runs west of Bedok Jetty across about 7 kilometres, so the stretch of water these 4 projects face is directly involved. Sea-facing high floors carry the exposure. Lower and inland-facing stacks were never selling a sea view in the first place. What no one can tell you yet is the finished profile, because the reclamation itself follows the preparatory works.
No. All 4 have a higher median psf in 2026 than in 2021. Mandarin Gardens is the one to watch, having moved sideways since 2023 at around $1,283 to $1,327 psf.
The collective sale math was already difficult. Mandarin Gardens would start from roughly $1.9 billion before any premium. Lease decay raises the lease top-up cost and is the more immediate obstacle.
48 years at Neptune Court, 50 at Laguna Park and Lagoon View, and 55 at Mandarin Gardens, measured in 2026 from lease commencements of 1975, 1977 and 1982.
Not on its own. The district is 94% freehold, and the freehold picture is the more useful lens for most buyers. These 4 projects are among the 26 leasehold exceptions, which is why the lease conversation dominates here and almost nowhere else in District 15. 2,753 households own a decision here, and the honest version is duller than the rumour: the lease is the live issue, the reclamation now has a start date and no end date, and the market has so far priced neither as a crisis. If you want to know what your specific unit is worth against the 400 recorded resales in these 4 projects, message me on WhatsApp and I will send you the comparables for your stack.
Hi 
We offer private property consultations for readers. Interested?