Buyer Guides
Published on
January 1, 2026

How to Upgrade From HDB to Condo Without Paying ABSD in Singapore (2026)

Author
Pei Xuan
Peixuan runs every LiveFree deal from offer to key collection, covering the paperwork, deadlines and handover, so nothing falls through the cracks. She is a CEA-registered salesperson with PropNex Realty (Reg. No. R069001J).
Table of content

Table Of Contents

Contact Us

Find The Right Home
Request
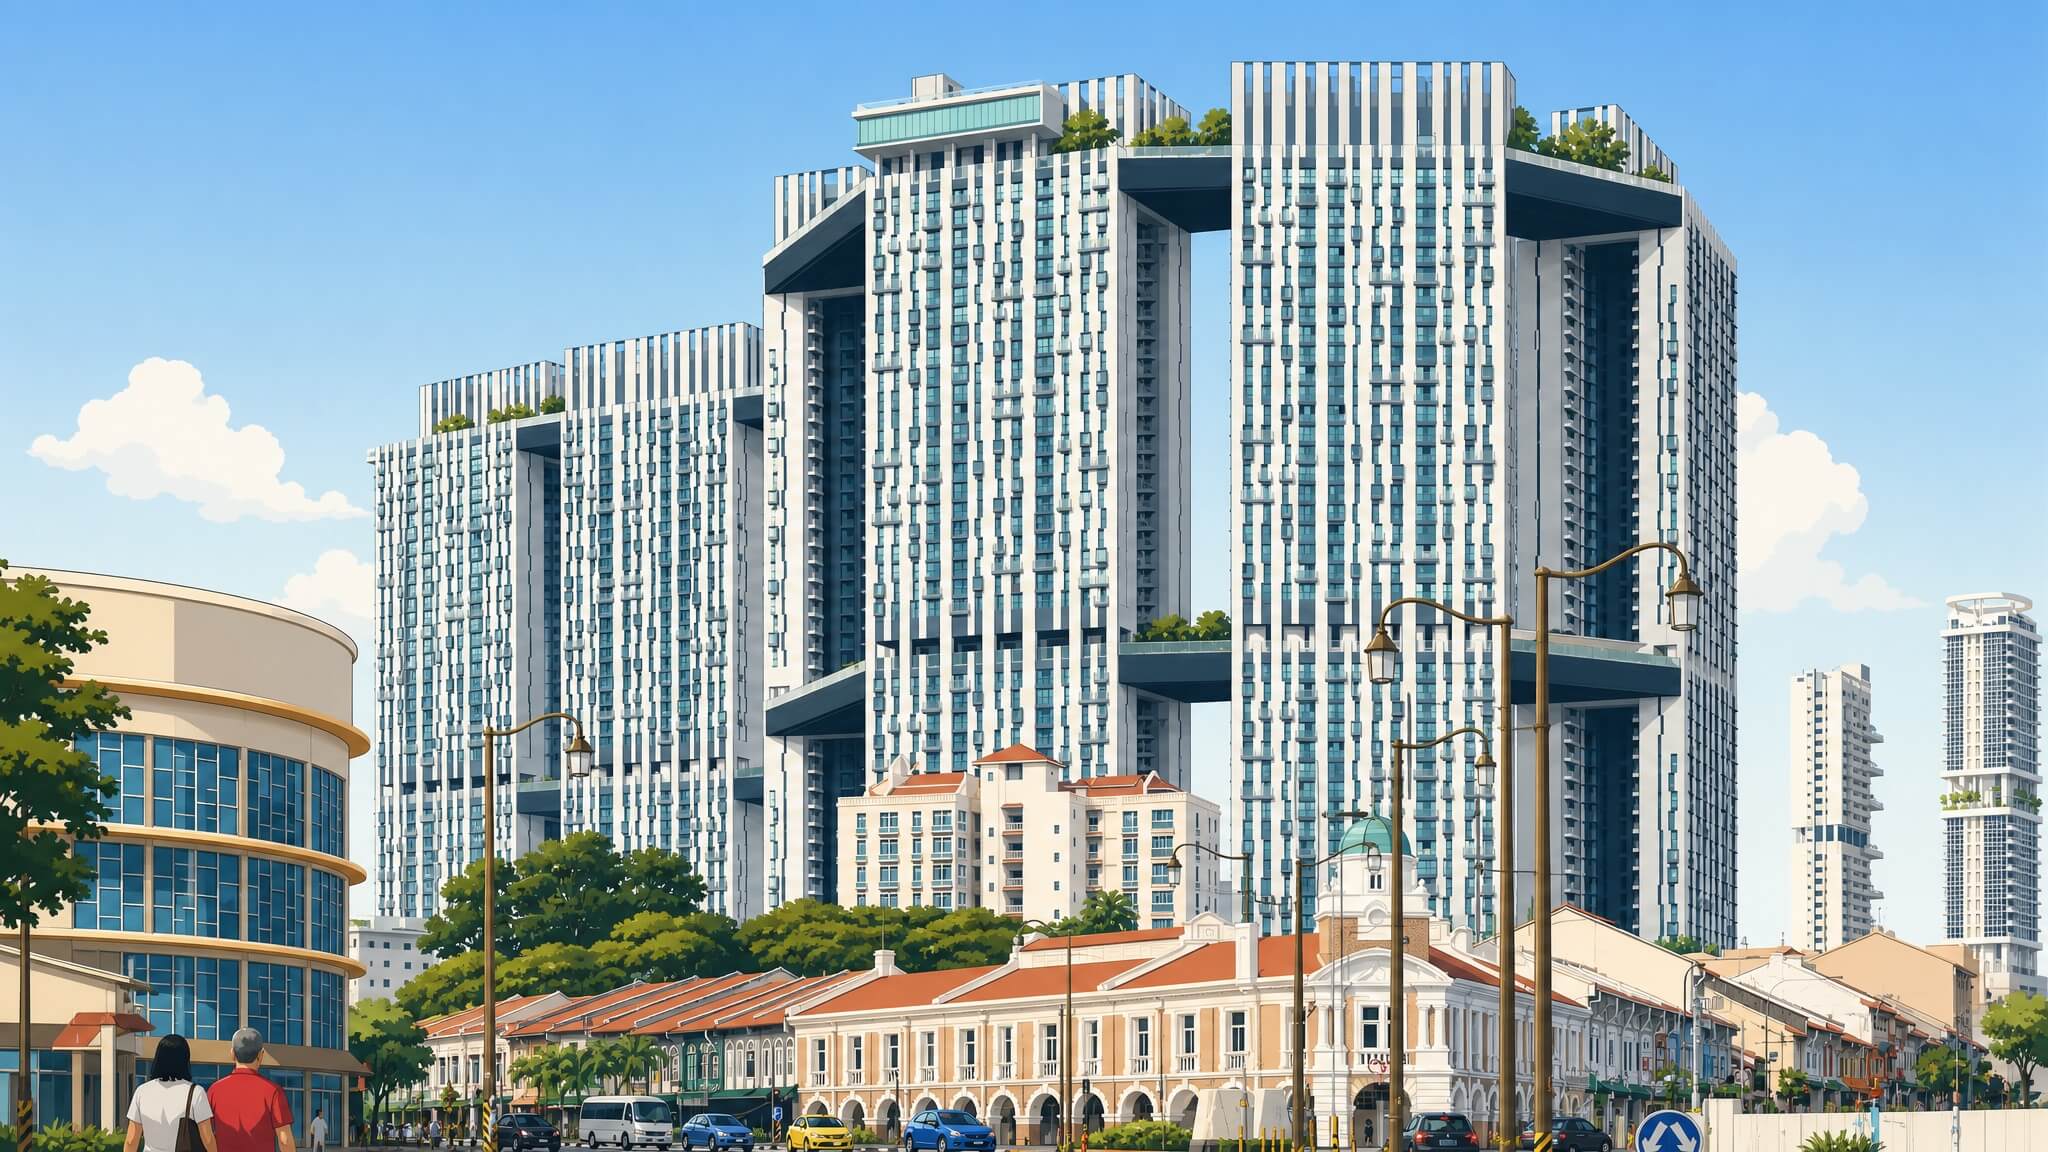
Pinnacle at Duxton HDB towers - upgrading from HDB to condo without paying ABSD in Singapore

ABSD in Singapore is the tax that scares every upgrader — and the short answer is: never own two residential properties at the same time, or structure your timeline so the ABSD you pay upfront comes back as a refund. Every legitimate strategy is a version of one of these two ideas.

For most HDB owners planning an upgrade, the single biggest fear is Additional Buyer’s Stamp Duty.

The rates explain why. As at 1 January 2026, a Singapore Citizen buying a second residential property pays 20% ABSD. On a $1.8 million condo, that is $360,000 — often more than the entire cash proceeds from selling the flat.

The good news: genuine upgraders are not the target of ABSD, and the rules give you clear, legal pathways to avoid it entirely. The bad news: every pathway punishes sloppy execution.

Let’s break down the three that matter.
1. Sell First, Then Buy — The Safest Path

How it works

  • Sell your HDB and legally complete the sale
  • At the point you exercise your condo purchase, you own zero properties
  • No ABSD is payable. Full stop.

Why most upgraders choose it

  • Zero ABSD risk, no deadlines, no refund paperwork
  • You know exactly how much cash and CPF you have before committing
  • Loan assessment is cleaner without an existing mortgage

The real costs

  • You may need somewhere to stay in between — renting for a few months, or staying with family
  • Moving twice is genuinely painful with kids
  • You are exposed to the market moving up while you search

One nuance worth knowing: the sell-first path can involve an extension of stay negotiated with your HDB buyer (up to 3 months), which softens the double-move problem considerably.

Best for: risk-averse households, buyers who want certainty on their numbers before committing, and anyone whose finances would be stretched by fronting ABSD.
2. Buy First, Then Sell — The ABSD Refund Route

How it works

  • Buy the condo while still owning your HDB
  • Pay the 20% ABSD upfront
  • Sell the HDB within 6 months of the condo purchase (for a completed/resale unit) or within 6 months of TOP/CSC (for an uncompleted new launch)
  • Apply to IRAS for a full ABSD refund

The eligibility rules, precisely

  • You must be a married couple with at least one Singapore Citizen
  • The refund applies to the couple’s second property purchased jointly
  • The first property must actually be sold within the window — no extensions for a slow market

Singles, take note: this refund route is not available to you. Sell-first is effectively your only clean path.

Why buyers choose it

  • Move only once, directly from flat to condo
  • Secure the exact unit you want before selling
  • Buying a new launch stretches the timeline generously — your 6-month clock only starts at TOP, which can be 3–4 years away

The risks

  • You need the ABSD amount in cash or CPF upfront — six figures parked for months
  • If your HDB does not sell within the deadline, the refund is gone. Permanently.
  • Two mortgages and bridging costs in the overlap period

Best for: financially strong couples, and especially new-launch buyers, where the long runway to TOP makes the refund conditions comfortable to meet. Before committing, be honest about your flat’s marketability — what your HDB is really worth, and what holding it costs, determines whether this route is safe or reckless.

3. Decoupling — Powerful, but Mostly Not for HDB

How it works

  • One spouse transfers their share of the current property to the other
  • The exiting spouse becomes a non-owner — a “first-timer” in ABSD terms
  • They buy the next property in their sole name at 0% ABSD

The fine print that matters

  • HDB flats generally cannot be decoupled — ownership transfers between spouses are only allowed in limited circumstances (divorce, death, financial hardship), not for tax planning
  • Decoupling is therefore a private-property strategy: relevant if you already own a condo and want to buy a second
  • It is not free: the transfer itself attracts stamp duty (and possibly seller’s stamp duty), plus legal fees on both sides, and the remaining owner must qualify for the loan alone

For a typical HDB upgrader, decoupling is a distraction. Where it earns its keep is one move later — structuring the condo purchase (say, 99% / 1% is a separate conversation with real risks; get proper legal advice) so a future second purchase stays ABSD-free.

4. The Timeline Is the Strategy

Whichever path you pick, the actual work is sequencing:

  • Sale completion date vs purchase completion date
  • CPF refund flowing back before it is needed for the next downpayment
  • Loan approval (IPA) locked in before you commit either way
  • Temporary housing arranged if there is a gap

And one 2026-specific caution: the 15-month wait-out period applies to private owners moving down to a resale HDB flat, not to upgraders — but it means your backup plan of “just buy a flat again if things go wrong” is slower than you think. Plan forward, not backward.

A poorly-sequenced upgrade produces the worst outcomes we see: surprise ABSD, bridging stress, or a panic purchase of the wrong condo. Our full HDB Upgrading Roadmap walks the sequence step by step.

5. The Mistake That Costs More Than ABSD in Singapore

Here is the uncomfortable truth. We have watched buyers spend six months engineering a zero-ABSD move — and then buy a mediocre condo.

Avoiding 20% tax on the wrong asset is worse than paying stamp duty on the right one. The questions that actually determine your outcome:

  • Is the next property a genuinely stronger asset — entry price, location, future buyer pool?
  • Does the timing fit your family, not just the tax rules?
  • Can you hold comfortably if rates or prices move against you?

ABSD is a constraint to plan around. It is not the decision itself.

LiveFree Takeaways

  • Sell first if you want certainty and a clean balance sheet — accept the interim housing hassle
  • Buy first with the refund if you are a married couple with strong finances — and treat the 6-month deadline as sacred
  • Decoupling is for private property owners planning their next move, not for HDB upgraders today

Structure the move so ABSD never sticks — then spend your real energy choosing a condo your future buyer will queue for. The tax you avoid matters far less than the asset you end up holding.

This article is general information, not tax or legal advice. Confirm your specific situation with IRAS, HDB and your conveyancing lawyer before committing.

Frequently Asked Questions

How much is ABSD in Singapore in 2026?

Singapore Citizens pay 0% on their first residential property, 20% on the second and 30% on the third. PRs pay 5% / 30% / 35%, and foreigners pay 60% on any purchase.

Can I get my ABSD refunded?

Yes — married couples with at least one Singapore Citizen can claim a full refund if they sell their first home within 6 months of the second purchase (or its TOP for an uncompleted unit).

Do I pay ABSD if I sell my HDB before buying a condo?

No. If you complete the sale first, you own zero properties at the point of purchase, so no ABSD is payable — the sequencing details are in our HDB Upgrading Roadmap.

Does decoupling work for HDB flats?

Generally no — HDB ownership transfers between spouses are only allowed in limited circumstances, not for tax planning. Decoupling is a private-property strategy, and even there the CPF refund rules affect the sums.

Planning your own move? Contact Kelvin on WhatsApp — a question costs nothing.

More Articles

Ready to Take the Next Step?
Let's Build
Your Property Roadmap
Schedule a no-obligation consultation with our advisors. We’ll provide the clarity and data you need to make your next move with absolute confidence.
LiveFree © 2025. All Rights Reserved.

Hi
We offer private property consultations for readers. Interested?
Yes, show me