Hougang Central (site bounded by Hougang Central and Hougang Avenue 10, adjoining Hougang MRT and Hougang Bus Interchange)


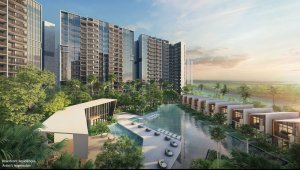
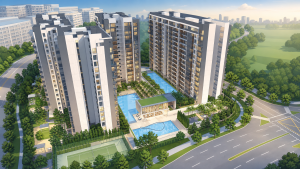
Hougang Central GLS is the working name for the mixed-use development coming to the Government Land Sales parcel at Hougang Central, and the case for it is short: 835 homes sitting on top of a new mall, the rebuilt Hougang Bus Interchange and direct access to Hougang MRT, in a town that has never had an address like it. UOL Group, CapitaLand Development and CapitaLand Integrated Commercial Trust took the site in January 2026, which means the whole of Hougang town centre is being rebuilt with the housing above it. Every figure on this page comes from the tender record, because at this stage nothing else has been released.
Hougang (NE14) on the North East Line is about 220m on foot and will connect straight into the development, with the interchange rebuilt underneath and Hougang Mall immediately beside the parcel. The station is also due to grow: Hougang becomes a Cross Island Line interchange, with the first phase targeted for around 2030. For drivers the KPE and the CTE are the working expressway pair here, though a town-centre address also inherits town-centre traffic.
Families get five primary schools inside the band that decides ballot priority: CHIJ Our Lady of the Nativity, Holy Innocents’ Primary School, Montfort Junior School, Punggol Primary School and Yio Chu Kang Primary School all fall within 1km under P1 registration, with six more in the 1km to 2km band. Our complete guide to the 2026 Primary One registration exercise walks the phases in order and our roundup of the top primary schools near District 19 condos puts it in context. On a parcel this large the measuring point may not sit where you assume, so check the school’s own distance checker once the blocks are sited.
The parcel runs to about 46,900 sqm, roughly 504,800 sqft, at a gross plot ratio of 2.5, which permits a gross floor area of about 1.27 million sqft. Around 40,000 sqm of that is commercial, so this is a serious mall rather than a token retail podium, and a retail landlord sitting in the consortium is the tell that someone intends to operate it long term.
Expected TOP is around 2030, the same window as the Cross Island Line works. Tenure is 99 years running from the January 2026 award, so a buyer taking keys at completion starts with roughly 95 years, close to the freshest a leasehold home gets. The site was also tendered after GFA harmonisation, so its strata areas will be measured on the current rulebook and its psf will compare like for like against other post-harmonisation launches, which is not true of the older resale stock nearby. What that costs is the next section.


CapitaLand is a leading Singapore developer formed in 2000, delivering homes and large-scale mixed-use projects locally and across Asia. In Singapore, its track record includes integrated landmarks such as CapitaSpring and CanningHill Piers, alongside recent residential launch J’den in Jurong East. It also redeveloped Funan, underscoring capability in retail and office-led mixed-use assets. Beyond residences, CapitaLand is active in retail, offices, integrated developments, and hospitality through The Ascott, with selective regional projects like Sycamore in Binh Duong New City. Buyers value its disciplined investment approach, sustainable asset management, and consistent delivery, supported by deep operating expertise and long-term asset stewardship.

UOL Group is a long-established, publicly listed Singapore developer with a consistent record of delivering well-designed, award-winning, sustainability-focused projects since the 1960s. In Singapore, recent launches such as Watten House, Pinetree Hill, AMO Residence and The Watergardens at Canberra show range across freehold and leasehold homes and different market segments. Beyond residential, UOL develops commercial and integrated projects and operates the Pan Pacific Hotels Group (Pan Pacific, PARKROYAL, PARKROYAL COLLECTION), underscoring strong execution and asset management capabilities. Buyers can expect considered layouts, durable specifications, reliable delivery timelines and steady after-sales support, aimed at long-term livability and value retention.


Integrated stock is structurally scarce, and that is the zoom-out that matters here rather than any district average. A project like this needs a state-owned transport parcel to exist, so each town gets roughly one, and Hougang Central GLS is Hougang’s turn. Our read on what the Hougang GLS site means for buyers covers the tender itself. Below: what the land rate implies about price, what the tender figures suggest about the product, and how the supply picture reads.
There is one hard number at this stage and it is the Land Bid. At the January 2026 award the consortium paid about $1.5 billion, or $1,179 psf per plot ratio, across the parcel’s 1.27 million sqft of permissible gross floor area. Work forward from a site cost of that size and the implied break-even carries construction, financing, marketing and margin on top, none of it small on a plot that also has to deliver a bus interchange.
Market commentary since the award has pointed to launch pricing meaningfully above $2,000 psf. That is other people’s read rather than a forecast of ours, and the gap between the two figures is the cost stack above, not an opinion about demand. Our review of the 2026 GLS land bids sets this tender against the year’s other sites.
Hougang’s surrounding resale stock trades well below that level, so Hougang Central GLS would arrive as the town’s price leader on day one. The premium buys the integration, the fresh lease and the rail timing. It also means the structural gain is in the price from the start, with the exit resting on the next buyer accepting a town-centre benchmark, which is a fair trade over a long hold and a poor one for a short flip.
Weighing whether to register interest? Speak to us before the price list lands and we will tell you what the arithmetic has to clear for this to work at your budget, honest advice, no pressure. WhatsApp us.
State it plainly, because plenty of pages will not. There is no unit mix, no floor plan, no price list and no showflat for Hougang Central GLS. Anything presented as a layout today is a guess, and we will not describe rooms that do not exist.
What the tender figures do support is a reasonable expectation of the product. Roughly 840,000 sqft of residential gross floor area across 835 homes averages a little over 1,000 sqft per unit before common areas are deducted, which points to a mainstream family mix rather than a shoebox-heavy investor block. Treat that as arithmetic on the tender figures, not a released mix. One physical detail is on the record and it is a good one: 835 carpark lots for 835 homes, a full one-to-one ratio on a plot that also has to carry a mall and a bus interchange.
The honest counterweight belongs here too. An 835-unit development above a bus interchange and a retail podium is a busy address, with bus movements from early morning, servicing at night and a public thoroughfare running under the homes. Stack selection will matter more at Hougang Central GLS than at almost any standalone project, and it is the first question to ask the day the floor plans appear.
Start at the pocket rather than the district. The Hougang Central subzone holds only four private developments and about 1,065 units in total, and 835 of those are this project. The existing private stock in the town centre comes to 230 homes, spread across Naung Residence, Midtown Residences and the ten-unit Parkwood Collection. Hougang Central GLS is the only project under construction here, and across the wider Hougang planning area it is the only one scheduled to complete after 2026.
Now the demand side, which is where this town is unusual. Hougang carries about 59,942 HDB flats across 605 blocks, and 44,200 of them are 4-room or larger, the flat types upgraders sell from. Set that against 17,982 private homes in the whole planning area, only 7,871 of them in projects completed from 2016 onward, and the shortage of fresh private stock against that upgrader pool is the clearest structural advantage for Hougang Central GLS. Our Hougang condo guide maps what the town currently offers, and our HDB upgrader guide for Hougang walks the move.
What cannot be shown is a caveat record, because nothing has sold. What stands in its place is the land rate, the consortium’s track record and the benchmark Hougang’s own resale market sets. Those are the three numbers we will run with you when the price list lands, using the framework in our comparison of new launch versus resale in District 19. The rail side is the other half: our analysis of how the Cross Island Line will affect District 19 property prices works through which pockets gain most from the 2030 interchange.
If you would rather own completed stock in the same catchment today, Kovan Residences and The Quartz are the obvious starting points, with Riverfront Residences and The Florence Residences covering the larger and newer end of the same market. All of them come with a shorter lease and no podium, which is the trade this page is about.
This suits families banking the five-school radius over a decade, upgraders leaving a flat in the same catchment who keep their schools and bus routes while moving into new private stock, and buyers who want the town’s best-connected address and can hold through a build running to about 2030. The URA Master Plan is the place to check what else is slated for this stretch before you commit.
Think about your eventual buyer too. By 2030 this would be the newest and best-connected address in a town whose rental supply is mostly older standalone condominiums and HDB flats, so the exit audience is both the next wave of upgraders and the tenant who wants a station downstairs. Run the letting maths against our rental yields guide before treating Hougang Central GLS as an investment rather than a home.
Fit matters in the other direction too. If you need keys inside two years, the completed estates above are the answer instead. If you want a quiet, low-density address, the pockets away from the town centre serve you better. And if your numbers only work by buying below the town’s benchmark rather than setting it, wait for the price list and judge it then.
Thinking about Hougang Central GLS? Register early, then talk to us before you commit. Developers typically take 12 to 24 months from award to launch, so a preview in the 2027 window is the realistic sequence, and expect the name to change when UOL and CapitaLand brand it. WhatsApp us.
Hougang Central GLS has 835 residential units.
Floor plans have not been released yet. Register with us and we’ll send the full set, plus our read on the best stacks, the day they are out.
The site is about 46,900 sqm (roughly 504,800 sqft), with a gross plot ratio of 2.5 and a permissible gross floor area of about 1.27 million sqft.
Hougang Central GLS is 99-year leasehold.
No, Hougang Central GLS is a 99-year leasehold development.
Hougang Central GLS is developed by UOL Group, CapitaLand Development and CapitaLand Integrated Commercial Trust (CICT).
The site sits at Hougang Central, directly beside Hougang MRT (NE14) and Hougang Bus Interchange, next to Hougang Mall in the heart of Hougang town centre.
Hougang Central GLS is in District 19 (Hougang, Punggol, Sengkang), in the Outside Central Region (OCR).
Hougang (NE14) is about 220m away and connects directly into the development. The same station becomes a Cross Island Line interchange when CRL Phase 1 opens, targeted for 2030.
Schools within 1km: CHIJ Our Lady of the Nativity, Holy Innocents’ Primary School, Montfort Junior School, Punggol Primary School and Yio Chu Kang Primary School.
Primary schools within 2km: CHIJ Our Lady of the Nativity, Holy Innocents’ Primary School, Montfort Junior School, Punggol Primary School, Yio Chu Kang Primary School, Hougang Primary School, North Vista Primary School, Palm View Primary School, Rosyth School, Xinghua Primary School and Xinmin Primary School. Of these, the first five fall inside the 1km P1 registration radius. Secondary options nearby include Holy Innocents’ High School, Montfort Secondary School, Hougang Secondary School and Serangoon Secondary School.
Hougang Mall sits immediately beside the site, and the development itself will include about 40,000 sqm of commercial space. Also within about 2km: Hougang 1, Hougang Green Shopping Mall, Kang Kar Mall and Buangkok Square Mall.
Yes – Punggol Park, Hougang Crest Sports Park, Harmony Park and the Sungei Serangoon Park Connector all sit within about 2km.
Beyond the mall and interchange in the development itself, the Hougang civic and sports cluster sits within about 1km: Hougang Stadium, Hougang Swimming Complex, Hougang Sports Hall, Hougang Polyclinic and the Hougang Public Library.
No units have been sold, so there is no transacted PSF yet. The consortium paid $1,179 psf per plot ratio for the land, and market commentary since the award has pointed to launch pricing meaningfully above $2,000 psf. Treat any figure quoted today as an estimate – ask us for the official price list when it is released.
It holds the strongest structural position in Hougang: a fully integrated development on top of an MRT station that becomes a Cross Island Line interchange around 2030, with the mall and bus interchange underneath. Integrated stock is scarce – each town gets roughly one – and it historically commands a resale premium over standalone neighbours. The open question is entry price, since the consortium paid $1,179 psf per plot ratio. Speak to us before you commit.
Yes. Five primary schools sit within 1km – CHIJ Our Lady of the Nativity, Holy Innocents’ Primary, Montfort Junior, Punggol Primary and Yio Chu Kang Primary – with Hougang Mall, the library, the polyclinic belt and Punggol Park all close by.
Hougang Central GLS is the working name for the 99-year leasehold mixed-use development on the Hougang Central Government Land Sales site, awarded in January 2026 to a UOL Group, CapitaLand Development and CICT consortium. It will integrate 835 homes with a retail mall, the bus interchange and direct MRT access. The project name will be announced closer to launch.
Hougang Central GLS is expected to obtain TOP in 2030.
The launch date has not been announced. The site was awarded in January 2026, so a sales launch is expected once planning approvals and the project name are finalised. Register your interest with us for first notice of the preview.
Yes. Foreigners can buy Hougang Central GLS because it is a private residential development. Foreigners pay 60% Additional Buyer’s Stamp Duty (ABSD) on top of the purchase price.
The showflat is not open yet. Contact us and we’ll arrange a preview slot as soon as the sales gallery opens.
You can book a viewing with our appointed sales team:
Kelvin Sin 9722 2222
Chew Peixuan 9101 5301
Hi 
We offer private property consultations for readers. Interested?